PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120398

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120398
Europe Social Media Analytics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Europe social media analytics market size reached USD 5.12 billion in 2026 and is projected to climb to USD 10.34 billion by 2031, advancing at a 15.09% CAGR through the forecast period.
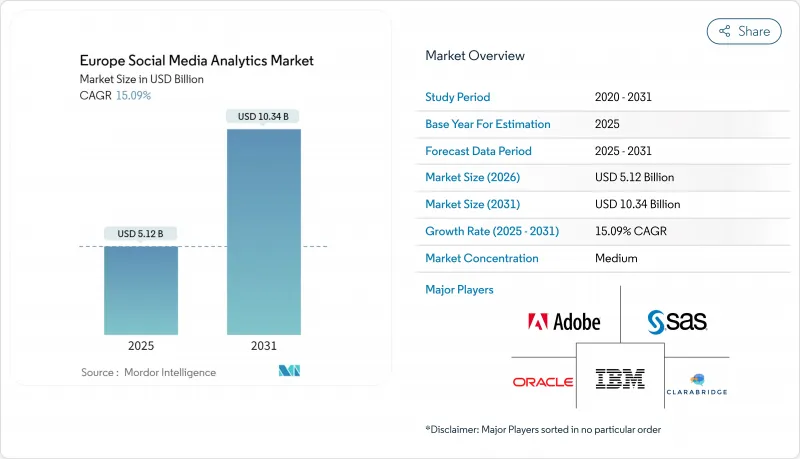
This report is Segmented by Component (Monitoring, Measurement, and Analytics and Insight), Mode of Deployment (On-Premise, and Cloud), End-User Vertical (Banking, Financial Services and Insurance (BFSI), IT and Telecom, Retail, Healthcare, and More), Organization Size (Small and Medium Enterprises, and Large Enterprises), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Europe Social Media Analytics Market Trends and Insights
Rising Adoption of AI-Powered Customer Insights Platforms
Adobe's March 2025 integration of IBM watsonx into Adobe Experience Platform let marketers query sentiment in plain language rather than SQL, accelerating insight cycles from weeks to hours. Salesforce matched the move the same month, launching Marketing Intelligence with 13 prebuilt connectors that fuse paid-social metrics and organic sentiment in a single view. Such releases reposition artificial intelligence from bolt-on feature to system backbone. Vendors now compete on corpus breadth and multilingual accuracy because sentiment classifiers trained largely on English misread nuance in Romance and Germanic languages, a gap underscored by the European Language Equality project.
Increasing Digital Ad Spending by European Enterprises
The AdEx Benchmark Study logged EUR 15.394 billion (USD 16.89 billion) in 2024 social-media ad spend, a 32.8% jump that eclipsed display and search growth. Social video represented 56% of that outlay, reflecting platform algorithms that elevate short-form clips. As a result, brands insist on attribution engines that align impression delivery with downstream sales, while simultaneously meeting Digital Services Act disclosure requirements. Analytics suites that automate compliance reporting therefore shift from optional to mandatory.
Stringent GDPR Compliance Constraints
National regulators in Germany, France, and Belgium have issued cumulative fines exceeding EUR 1 billion (USD 1.1 billion) for unlawful profiling since 2018. Platforms must secure explicit consent before processing personal data, yet sentiment analysis often infers demographics from public posts, a practice regulators scrutinize. Cloud providers also face residency mandates that compel local data centers, inflating costs that vendors must pass to customers.
Other drivers and restraints analyzed in the detailed report include:
- Growing Demand for Real-Time Consumer Sentiment Analysis
- Emergence of Regulatory Mandates for Algorithmic Transparency Driving Analytics Demand
- Fragmented Data Access Due to Platform API Restrictions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Analytics and Insight claimed 46% of 2025 revenue, the top component share of the Europe social media analytics market, and is predicted to post a 15.87% CAGR through 2031. The segment's momentum stems from enterprises that favor prescriptive outputs over raw dashboards, illustrated by Adobe's Agent Orchestrator, which automates audience segmentation and testing. Monitoring and Measurement still capture essential feeds, yet open-source stacks like Kafka shrink their value, shifting budgets toward predictive utilities that flag sentiment inflection points in advance.
General Data Protection Regulation pressure reinforces the tilt toward Insight modules because aggregated outputs carry lower legal exposure than user-level logs. Vendors bake anonymization directly into pipelines to satisfy German and French regulators, thereby combining compliance and decision support in a single workflow.
Cloud deployment generated 71% of 2025 revenue and will expand at a 16.12% CAGR through 2031, eclipsing on-premise alternatives in the Europe social media analytics market. Multilingual natural-language processing models scale compute during campaign surges then idle once traffic recedes, a pattern that favors utility pricing. Small and medium enterprises, the fastest-growing customer group, gravitate toward operating-expense subscriptions that avoid hardware acquisition.
On-premise installations persist in banking and government due to residency mandates. Financial institutions follow European Central Bank outsourcing guidelines that hold boards liable for data-security lapses even in cloud contracts. Hybrid patterns emerge: raw data remain behind corporate firewalls, while sanitized aggregates move to public clouds for model training.
Complete Report Scope:
- By Component
- Monitoring
- Measurement
- Analytics and Insight
- By Mode of Deployment
- On-Premise
- Cloud
- By End-user Vertical
- Banking, Financial Services and Insurance (BFSI)
- Information Technology and Telecommunication
- Retail
- Healthcare
- Government Services
- Media and Entertainment
- Utilities
- Transportation and Logistics
- Other End-user Verticals
- By Organization Size
- Small and Medium Enterprises
- Large Enterprises
- By Country
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
List of Companies Covered in this Report:
- Adobe Inc.
- Oracle Corporation
- Salesforce Inc.
- International Business Machines Corporation
- SAP SE
- SAS Institute Inc.
- Talkwalker Sarl
- Brandwatch (part of Cision US Inc.)
- Sprout Social Inc.
- Hootsuite Inc.
- Meltwater B.V.
- NetBase Solutions Inc.
- Khoros LLC
- Emplifi Czech Republic a.s.
- Qualtrics International Inc.
- Zoho Corporation Private Limited
- Google LLC
- Meta Platforms Inc.
- Ipsos Group S.A.
- Digimind
- Clarabridge (part of Qualtrics)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of Social Media Users Across Europe
- 4.2.2 Rising Adoption of AI-Powered Customer Insights Platforms
- 4.2.3 Increasing Digital Ad Spending by European Enterprises
- 4.2.4 Growing Demand for Real-Time Consumer Sentiment Analysis
- 4.2.5 Emergence of Regulatory Mandates for Algorithmic Transparency Driving Analytics Demand
- 4.2.6 Localization Requirements for Multilingual Sentiment Models
- 4.3 Market Restraints
- 4.3.1 Stringent GDPR Compliance Constraints
- 4.3.2 High Implementation Costs for Advanced Analytics Tools
- 4.3.3 Growing Consumer Pushback Against Social Listening Perceived as Surveillance
- 4.3.4 Fragmented Data Access Due to Platform API Restrictions
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Buyers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Monitoring
- 5.1.2 Measurement
- 5.1.3 Analytics and Insight
- 5.2 By Mode of Deployment
- 5.2.1 On-Premise
- 5.2.2 Cloud
- 5.3 By End-user Vertical
- 5.3.1 Banking, Financial Services and Insurance (BFSI)
- 5.3.2 Information Technology and Telecommunication
- 5.3.3 Retail
- 5.3.4 Healthcare
- 5.3.5 Government Services
- 5.3.6 Media and Entertainment
- 5.3.7 Utilities
- 5.3.8 Transportation and Logistics
- 5.3.9 Other End-user Verticals
- 5.4 By Organization Size
- 5.4.1 Small and Medium Enterprises
- 5.4.2 Large Enterprises
- 5.5 By Country
- 5.5.1 United Kingdom
- 5.5.2 Germany
- 5.5.3 France
- 5.5.4 Italy
- 5.5.5 Spain
- 5.5.6 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)}
- 6.4.1 Adobe Inc.
- 6.4.2 Oracle Corporation
- 6.4.3 Salesforce Inc.
- 6.4.4 International Business Machines Corporation
- 6.4.5 SAP SE
- 6.4.6 SAS Institute Inc.
- 6.4.7 Talkwalker Sarl
- 6.4.8 Brandwatch (part of Cision US Inc.)
- 6.4.9 Sprout Social Inc.
- 6.4.10 Hootsuite Inc.
- 6.4.11 Meltwater B.V.
- 6.4.12 NetBase Solutions Inc.
- 6.4.13 Khoros LLC
- 6.4.14 Emplifi Czech Republic a.s.
- 6.4.15 Qualtrics International Inc.
- 6.4.16 Zoho Corporation Private Limited
- 6.4.17 Google LLC
- 6.4.18 Meta Platforms Inc.
- 6.4.19 Ipsos Group S.A.
- 6.4.20 Digimind
- 6.4.21 Clarabridge (part of Qualtrics)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

